Introduction
The first bank visit can feel heavy. Forms are long, words are strange, and queues move slowly. Many farmers return home unsure what went wrong. Often a single missing paper or one unasked question was the cause. Clear farming information in Hindi can prepare you before you step inside. MAHTO is a Hindi-first rural knowledge platform. It explains agriculture, government schemes, livestock, mandi prices, and village business in plain words. It is not a government website. This blog is a checklist for a first-time Kisan Credit Card applicant. It also covers papers, crops, animals, and side income. Read it once at home, then carry the main points with you.
What Does Bank Credit for Farming Mean?
Bank credit means borrowing money from a bank and paying it back with interest. For farming, the money covers seed, labour, water, and other crop costs. You repay after the harvest sells. The bank studies your land, your papers, and your past record before it agrees. It also sets a limit on how much you can draw. Credit is a tool, not a gift. Used well, it fills the gap before income arrives. Used carelessly, it becomes a burden that follows you into the next season.
Why This Matters for Farmers and Villages
Farm costs come first, and income comes later. Without bank credit, many families turn to local lenders. Those loans often carry very high interest, and the pressure can force a hasty sale. A bank loan is usually cheaper and has clear rules. When more families learn how to use it well, money stays in the village. Fewer people fall into debt traps. Banks also learn to trust local farmers. Over time, that trust makes the next loan easier. Careful borrowing is a skill, and the whole village can learn it together.
Farming Information in Hindi: Why Simple Language Helps
Loan forms use heavy terms. Words like collateral, margin money, and sanction confuse even educated readers. Farming information in Hindi explains them in daily speech. Collateral means something of value that you pledge as security. Sanction means the bank has approved the loan. Limit means the highest amount you may draw. Once these words are clear, you can ask the staff direct questions. You can also read the paper before you sign. Never sign a form you do not understand. Ask the staff to explain, and take a copy for your records.
Government Schemes for Farmers
Several government schemes for farmers connect to bank credit. Some states give interest support to farmers who repay on time. Crop insurance is often linked to loans, so ask what your loan includes. Training and group programmes may also help you plan better. Rules, rates, and dates differ by place and can change. Ask your bank and block agriculture office what applies to you now. MAHTO.IN explains scheme basics, documents, and common mistakes in plain steps. Use it to prepare your questions. Official offices and banks give the final answer, so never pay a middleman for approval.
PM Kisan eKYC Explained Simply
Clean identity records help every bank visit. If you receive PM-Kisan benefits, keep PM Kisan eKYC complete. It is an online identity check that confirms the right person receives the scheme benefit. Check your status on the official portal. Make sure your name, bank account, and mobile number match your papers. A name spelled differently on two documents can slow your loan too. Fix such errors before the visit. A common service centre can help if the online steps fail. Steps may change, so follow the official portal. Never share an OTP.
Kisan Credit Card: What Farmers Should Know
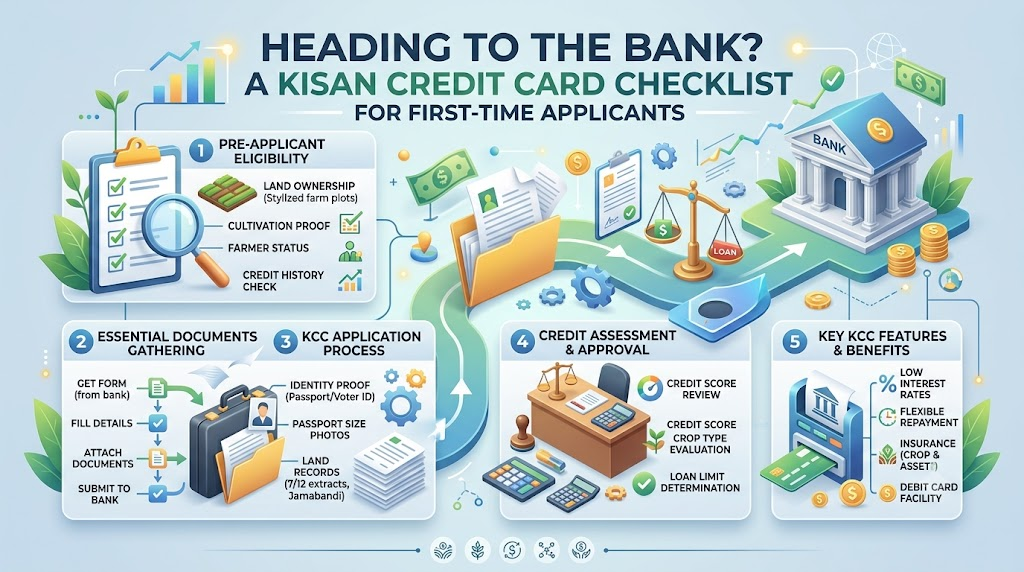
Here is the main topic. The Kisan Credit Card is a bank facility that gives eligible farmers credit for crop and related needs. Tenant farmers and animal keepers may be covered in some cases, and banks decide this. Start with a short checklist. Carry ID proof, address proof, and land or tenancy papers. Bring recent photos and your bank passbook. Ask about the limit, interest, repayment dates, and any extra charges. Ask what happens if the crop fails. Ask whether insurance is linked. Write the answers in a notebook. Rules differ by bank, so confirm current terms.
How to Check Mandi Prices
Repayment depends on selling well. So learn how to check mandi prices before you borrow. Use official market portals, farm apps, and mandi notice boards. Call trusted traders and compare offers. Note the rates for your crop over several weeks. Then estimate whether the season can repay the loan without a forced sale. Add transport and handling costs to your math. If the numbers look thin, borrow less. A clear market view helps you set a safe repayment plan, and it shows the bank that you are a careful borrower.
How to Grow Paddy
A paddy loan should follow a paddy plan. If you plan how to grow paddy, write down each cost before you visit the bank. Include land work, seed, nursery, transplanting labour, water, weeding, and harvest help. Ask your agriculture office for suitable seed and local advice on inputs. Never guess fertilizer or spray amounts. A written plan shows the bank that you know your crop. During the season, keep every bill. After harvest, compare real costs with your plan. That habit helps you borrow better next time.
How to Start Organic Farming
Natural farming may need less cash for chemicals but more for labour and compost. If you want to learn how to start organic farming, ask the bank whether it treats such costs differently. Prepare a simple plan for one trial plot. List compost material, labour, and any natural inputs you will buy. Start small so the loan stays small. Keep notes on yield and cost each season. Results may be slow at first. Learn label rules before selling produce as organic. A modest loan is safer while you learn.
How to Start Goat Farming
Some banks may include animal husbandry needs in certain credit facilities. Ask your branch what applies. If you think about how to start goat farming, prepare a short plan before you go. List the shed, animals, feed, water, and vet costs. Show how you will sell and when. Build a dry, raised shed and buy a few healthy animals from trusted sellers. Meet a local veterinarian early. Never borrow to buy a large herd on the first day. Start small, keep records, and grow slowly.
Livestock Farming Information
Useful livestock farming information helps you explain your plan to a bank officer. Dairy, poultry, and fish each have different costs and income cycles. Dairy gives daily income but needs fodder and early work. Poultry turns quickly but needs strict cleanliness. Fish ponds need water checks and patience. Vaccination protects animals from many common diseases, and your veterinarian sets the schedule. Balanced feed supports growth. A clear, honest plan helps the bank see the risk and your preparation. Choose the animal your family can manage daily.
Village Business Ideas
Not every business fits a crop loan. Village business ideas often need a separate loan type. Ask your bank which product suits a small shop, stitching unit, or repair stall. Prepare a one-page plan with what you will sell, to whom, and at what cost. Count tools, rent, and your own time. Test demand with a few buyers first. Keep home money and business money apart. Training programmes and bank advice can help you plan. No idea guarantees profit, so borrow only what the plan supports.
Table: Farming and Rural Income Options at a Glance
| Option | What It Involves | Who It Helps |
|---|---|---|
| Kisan Credit Card | Bank credit for crop costs with set limit and dates | Farmers needing seasonal funds |
| Government schemes for farmers | Interest support, insurance links, training | Borrowers who repay on time |
| PM Kisan eKYC | Online identity check and matched records | PM-Kisan beneficiaries |
| How to check mandi prices | Testing whether sales can repay the loan | Growers planning repayment |
| How to grow paddy | Written cost plan shown to the bank | Farmers with irrigated land |
| How to start organic farming | Small trial plot and a small loan | Farmers testing natural methods |
| How to start goat farming | Short plan with shed, feed, vet costs | Families with small space |
| Livestock farming information | Comparing animal costs and income cycles | Families choosing animals |
| Village business ideas | Separate loan type and one-page plan | Youth, women, small groups |
Common Mistakes Farmers Make
- Going without papers. Make a folder with copies before you leave home.
- Signing without understanding. Ask staff to explain every line.
- Not asking about charges. Get all fees stated clearly.
- Forgetting the repayment date. Mark it on your phone and in your book.
- Ignoring PM Kisan eKYC. Mismatched records slow many processes.
- Borrowing more than the crop needs. A smaller loan is easier to repay.
- Planning repayment without knowing how to check mandi prices for your crop.
- Paying agents for help with government schemes for farmers. Ask the bank for free guidance first.
- Using farm credit for unrelated spending. Keep it for crop needs.
- Hiding trouble from the bank. Speak early if a crop fails.
A Simple Example
This is a fictional example. A farming family decides to ask their bank about a Kisan Credit Card. First, they read credit guides on MAHTO.IN and write down their questions. Next, they gather ID, address proof, land papers, and photos in one folder. They check their names against each paper and fix one spelling error. Then they list expected seed and labour costs for paddy. Before the visit, they note market rates from two sources. At the bank, they ask about limit, interest, charges, and insurance. They take notes and borrow only what the plan supports. Each step is confirmed with the branch.
How MAHTO Can Help
MAHTO helps families go to the bank with confidence. Its farming pages cover crops, irrigation, soil testing, fertilizers, pest control, and crop calendars, including how to grow paddy and how to start organic farming. Scheme pages explain PM-Kisan, PM Fasal Bima Yojana, Kisan Credit Card, and Soil Health Card. They share eligibility, benefits, documents, application steps, and common mistakes. Livestock pages offer livestock farming information on dairy, poultry, fish, goats, and feed. Business pages share village business ideas for many budgets. The aim is farming information in Hindi that makes forms less scary. MAHTO is not an official portal. It cannot promise income, subsidy, or loan approval.
Frequently Asked Questions About First-Time Bank Credit
- How does farming information in Hindi help me before a bank visit?
It explains loan words like limit and sanction in daily speech. You can prepare questions and read forms with more confidence. Family members can learn together. Still, the bank gives the final rules, and terms can change. - Which government schemes for farmers connect with bank loans?
Interest support and crop insurance may link with loans in some places. Rules differ by state and bank. Ask your branch and block agriculture office what applies now. Carry ID and land papers. Never pay anyone for a promised approval. - Can PM Kisan eKYC problems affect my loan process?
They may not decide a loan, but mismatched names and numbers can slow any form. If you are in PM-Kisan, complete eKYC on the official portal. Match your name, bank account, and mobile number across papers. A common service centre can help. - What papers do I need for a Kisan Credit Card?
Common papers include ID proof, address proof, land or tenancy records, and photos. Some banks ask for more. Call or visit the branch to confirm the list. Keep copies in one folder. Approval is the bank’s decision and is never guaranteed. - How to check mandi prices to plan loan repayment?
Use official market portals, mandi boards, and trusted traders. Track rates for several weeks. Subtract transport and handling costs. Estimate whether your sale can cover the loan. Borrow less if the numbers look tight. - How to grow paddy and show the bank a clear plan?
Write each cost, from land work to harvest labour. Ask your agriculture office for seed and input advice. Do not guess fertilizer or spray amounts. Keep bills during the season. Compare your plan with real spending after harvest. - Should I borrow a lot when I learn how to start organic farming?
No, start with a small trial plot and a small loan. Note costs and results each season. Yields may be slow at first. Ask local experts about training and label rules. Grow only after you see steady results. - How to start goat farming if I want bank help?
Ask your branch which loan type fits animal keeping. Prepare a short plan with shed, feed, vet costs, and selling plans. Start with a few healthy animals. Meet a veterinarian before buying. Never borrow for a large herd at the start. - Where can I get livestock farming information to support my plan?
Ask your district veterinary or animal husbandry office. Farm training centres also help. Plain guides on MAHTO.IN can prepare your questions. Compare dairy, poultry, and fish costs before choosing. Ask a veterinarian before treating any illness. - Does MAHTO share village business ideas that suit small loans?
Yes, MAHTO shares simple village business ideas with planning tips. It is a Hindi-first learning platform, not a government site. It cannot promise income or loan approval. Ask your bank which loan type fits your plan.
Final Thoughts
A good bank visit begins at home. Gather your papers, fix any name mismatch, and write your questions. Keep PM Kisan eKYC complete if you are in the scheme. Ask about every charge before you sign, and mark your repayment date. Learn how to check mandi prices so your plan can repay the loan. Build skills like how to grow paddy, how to start organic farming, and how to start goat farming step by step, with small, safe loans. Use farming information in Hindi, steady livestock farming information, and honest village business ideas to plan. Confirm government schemes for farmers on official sources. MAHTO.IN will keep sharing simple guides for rural families.